
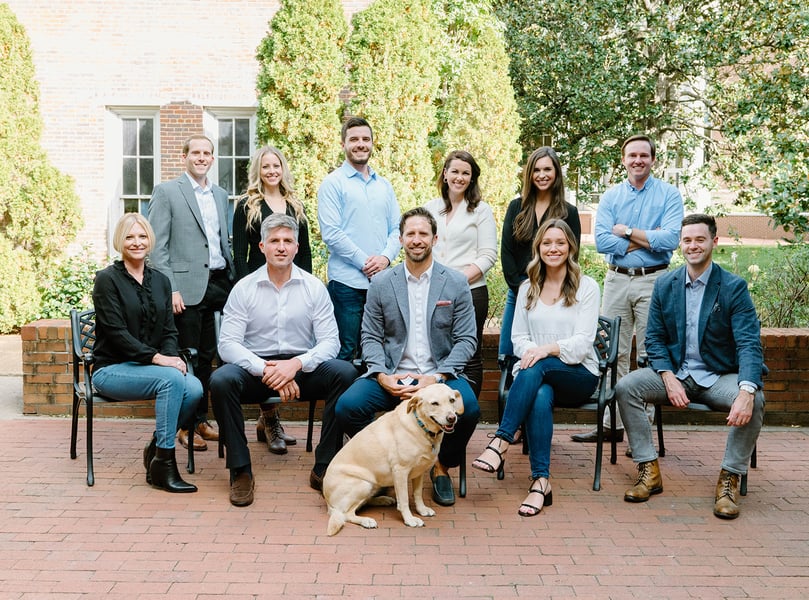
Working out of Nashville, Tennessee, David Adams has a lot of experience dealing with rock stars.
As the founder of Adams Wealth Partners, he says that living in the heart of ‘Music City’, seeing pop stars and country music legends is commonplace – as is having them on his books.
“We're in the heart of the city. I [handled] two or three big songwriters early in my career, helping them through catalog sales and [ultimately] became close with business managers in town which naturally led to referrals in such a tight knit circle.”
Working and living in the close-knit community means that successful writers will always talk to other writers – leading to a mass referral list that saw Adams’ business boom.
“Early on, that became our largest niche – the music industry,” says Adams. “It's probably still only 1/3 of our overall business, as we cater to business owners, divorcees, retirees, and corporate executives”
But dealing with creative types means understanding the importance of uniqueness – both in their songwriting and in their planning. For Adams, this begins with creating a customized plan which adheres to the celebrities’ fast moving, and often unpredictable, schedule.
“If we have a songwriter, they have very unique needs. They have periods of time where they have no income, and then they may write or produce a number one hit and then all of a sudden come into a chunk of money. Then there’s the sporadic royalty payments that we have to work around too, which can be consistent, but also unpredictable at times.”
Ultimately, this means adopting a holistic approach to financial planning – one which encompasses much more than portfolio management. For songwriters, this means looking at tax efficiency issues as well as future planning in song catalog sales.
“How do we make sure if we sell part of our life's work we’re able to be in a position where, going forward, we don't have to worry about money? Do we pay off our house? Do we fund kids’ college accounts? Do we set aside five or 10 years’ worth of income, really helping them customize a plan based on their unique income and cash flow needs? Because every career is different.”
In the case of musicians, the main area that Adams works on is royalty payments and catalog sales. As Adams explains, with songwriters they’re usually on a publishing deal which pays a very low salary to write music all day, in hopes of getting a song cut by a major artist.
“It’s a draw,” he tells Investment News. “It's a draw against a future hit that they may or may not [land]. And then, all of a sudden, they're lucky enough to write their first hit and they're going to be paying back all those draws. And if it took 10 years, then they may not actually start making money until hit two or three.”
This introduces a stream of income that is as variable as it is lucrative, depending on the song's popularity. For or those lucky few who accumulate a number of smash hits, there's an opportunity to sell their catalog, turning a lifetime of creative output into significant capital. This however, as Adams says, works very differently in the sports financial sector.
“A big athlete will get a contract that may be a huge chunk of money up front for a five commitment – but that will be highly, highly taxed. And it may be the only check they ever get.
“There's no guarantees depending on what sport they're into. And even if there is a guarantee, there's not a guarantee it's going to get renewed after five years. Then they may be 25 years old and they’ve already blown through that $5 million. There are all these horror stories you hear about athletes, because they spend all the money and [approximately] 50% of them are bankrupt after 3-5 amount of years. [Because] the average span of an athlete is usually two to four years. It's not always the Peyton Mannings or the Tom Bradys that you typically hear about.”
But, whether it’s music legends, sports superstars or just the average corporate Joe you’re dealing with, Adams believes a core component of any financial planning strategy hinges on brand management. Specifically, using technology and communication to reach the clientele you want to help.
"I've had a radio show, we have a podcast, we do blogs and social media. [It’s about] really trying to put out content on all the different platforms. Because what I've learned is so many different groups of people rely on on various modes of information. So as an advisor, you need to really have really fun (and a variety of) ways to get your story out [there].”
The main challenge with this, Adams concedes, is making the biggest impact you can in the short amount of time the video platform provides. As a consumer of this information, in order to combat this, Adams says find yourself a good holistic financial planner to help dig down to the nitty gritty and help you understand what information is relevant to your situation.
“They can take in all these bits of information, make notes about it and then go to a trusted source and say: ‘I was reading about this strategy with life insurance - does this apply to me?’ “I think there's a great lot of great content out there. You just have to be careful that you don't try to implement it all in a disconnected plan.”

Broker-dealer enforcement actions surged 66% as the SEC and state regulators cracked down on Ponzi schemes and digital asset fraud.

The deal adds $221 billion in AUM and bolsters Marsh's alternatives and model portfolio capabilities for advisors.

New Jackson research finds multi-generational financial obligations are leaving pre-retirees dangerously off track.

Sanctuary Wealth’s Vince Fertitta examines what wirehouse advisors may leave behind when a career ends in deferred compensation rather than a sale

Osaic's Empowered Independence reached roughly $20 billion in a year and a half as succession pressure pushes advisors toward becoming W-2 employees
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.

