
Healthcare employers have made retirement help easier to reach. They have not made it much more personal, and financial advisors who serve physicians and healthcare executives say that gap is their opening.
Ninety percent of healthcare employers surveyed by Transamerica offer virtual one-on-one retirement and financial wellness meetings, and 66% offer in-person sessions. Yet only 27% provide education tailored to specific employee groups, according to the insurer’s Retirement Plan Trends in Healthcare survey of 100 healthcare organizations. The findings echo Transamerica’s broader research on workers under severe financial strain. They also point to a client segment with high incomes, complicated benefits and very little time.
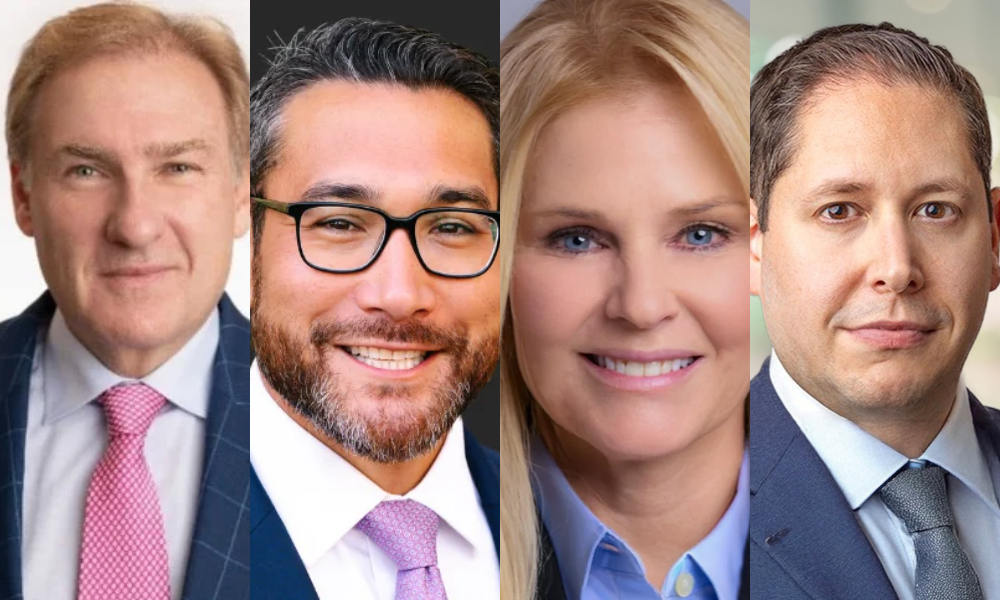
Physicians typically reach their peak earning years later than other high-income professionals, said Evan Potash, an executive wealth management advisor at TIAA Wealth Management. They spend years in training first, often while carrying significant student loan debt. Potash cited a 2023 TIAA Institute survey of healthcare workers. It found that 45% of retirement savers in the sector are putting away less than they otherwise would because of debt payments.
“As their careers progress, their income and ability to save can increase substantially, making it important to establish a financial plan that accounts for both their immediate priorities and long-term goals. The competitive nature of the healthcare industry can also create career mobility, adding another layer of complexity to long-term financial projections. That’s why consistent saving and regularly revisiting their financial plan are so important,” Potash said.
Iván Watanabe, managing partner at Opus Private Client, said medical training conditions doctors to give up autonomy at every step. That runs from admissions and Match Day through residency and the first attending contract. Many doctors then lean on colleagues for money advice. Advisors have long noted that physicians enter the workforce behind on retirement saving. Watanabe argues that habits formed in training compound the problem.
“Advisors need to respect that trust while challenging conventional wisdom and helping physicians recognize they have far more control over their financial futures than they’ve been conditioned to believe,” Watanabe said.
Among the healthcare organizations Transamerica surveyed, 70% offer a 403(b), 52% offer a 401(k) and 28% offer a nonqualified deferred compensation 457(b) plan. For a senior clinician or executive, that can mean several accounts with different tax treatment, distribution rules and risks.
Laura Gaynor, head of new business architecture and DC practice leader at Transamerica, said the advisor’s job is to show how those pieces fit together rather than judge each one in isolation.
“Advisors can help clients understand the role each available benefit can play, prioritize their choices and align those decisions with their broader financial and retirement goals. Ultimately, it’s about turning a collection of benefits into a coordinated retirement strategy,” Gaynor said.
Watanabe said the differences among 403(b), 401(a), and governmental and nongovernmental 457(b) plans matter most in three areas: access, distribution flexibility and employer credit risk. The IRS guidance on nongovernmental 457(b) deferred compensation plans notes that they differ sharply from governmental versions. For example, they cannot offer age-50 catch-up contributions. Deferrals in nongovernmental plans also generally remain subject to the employer’s creditors, which is the credit risk Watanabe flags. Before any of that, he said, protecting a physician’s earning power with adequate disability coverage comes first.
“Too often, physicians maximize tax-deferred retirement savings without considering whether they’re also building sufficient assets outside those plans. The objective is to balance tax efficiency with liquidity and flexibility, giving them the freedom to make career and lifestyle decisions on their own terms,” Watanabe said.
Potash said cutting today’s tax bill is a priority for many high earners. But it should not crowd out planning for how that income will be taxed later, as with employers using top hat plans to sweeten executive pay.
“That includes evaluating the balance between pretax and Roth contributions, understanding the timing of deferred compensation distributions and considering how different sources of retirement income may be taxed down the road,” he said.
Healthcare costs top the list of concerns. Transamerica found that 86% of healthcare employers identified healthcare costs as a pressing financial wellness need. Seventy percent cited understanding the cost of retirement and of healthcare in retirement.
“For this client segment, good advice means turning competing priorities into a clear, personalized course of action,” Gaynor said.
Potash and Gaynor both said flexible scheduling, such as early-morning or evening meetings, is only the starting point. They note that anticipating needs matters more than simply being available.
“It’s important to be proactive rather than waiting for clients to raise financial planning questions,” Potash said.
Gaynor made a similar point. “The strongest relationships are built when advisors make complex decisions easier and deliver relevant guidance before the client has to ask for it,” she said.
Mark B. Murphy, chief executive of Northeast Private Client Group, said the biggest misconception about high earners is that a large salary automatically builds wealth.
“I look at wealth building as a pyramid. You can’t build a pyramid from the top down and expect it to stand,” Murphy said. Building that foundation means protecting what clients have built, establishing cash confidence and setting a sound strategy, he said. Only then should they focus on growth, income beyond the paycheck or multigenerational wealth.
A physician fresh out of residency, a doctor 20 years into practice and an executive nearing retirement need different plans, Murphy said. “The plan has to evolve as the person evolves. You can’t create a financial roadmap once and assume it will serve someone for the next 30 years without adjustments,” he said.
Watanabe said advisors should keep asking two questions throughout a client’s career. “How much control do you want over your time, and how long do you envision working in your current setting? If entrepreneurship, practice ownership, or early retirement is a possibility, where their assets are held and how accessible they are can become just as important as how they’re invested,” he said.
For Murphy, that shift is the point of the work. “Ultimately, we’re not just managing money, we’re helping people make better decisions about their lives,” he said.

The mega-RIA keeps absorbing independent fiduciary firms as Cerulli data shows the fee-only segment losing asset share
This year's rush for the exits in private credit showed why investors must understand lockup periods before they weigh the return potential
Mercer adds specialized equity compensation tech and Big Four tax talent as UHNW demand for integrated tax planning intensifies.

Two CFP and CFA credentialed advisors unite planning and markets expertise under a new Richmond practice.
When the largest RIAs recruit for AI, they name Copilot, ChatGPT and Claude in job posts far more often than advisor-specific fintechs, Caddi data shows.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

