
Mortgage rates have climbed back above 7% for the first time in 20 months, and financial advisors say the move is changing how they treat the largest asset on many clients' balance sheets: the family home.
The average 30-year fixed mortgage rate rose to 7.03% in the week ended Sept. 24, 2026, up from 6.95% a week earlier and 6.30% a year ago, according to Freddie Mac's weekly Primary Mortgage Market Survey. It was the first reading above 7% since January 2025. The same day, the market yield on the 30-year Treasury bond touched roughly 5.5%, a level not seen since June 2004, while the 10-year note, which mortgage rates closely track, reached about 5.2%, its highest since 2007. The selloff came a week after the Federal Reserve raised its benchmark rate by a quarter point, its first move of the year.
For advisors, the combination creates an awkward planning problem. Housing is one of the biggest components of household wealth, but higher borrowing costs shrink the pool of buyers who can afford a given property and discourage owners who locked in cheap mortgages from selling – the so-called rate lock-in effect. The result is an asset that can look substantial on paper yet is harder to turn into cash on a client's timetable.
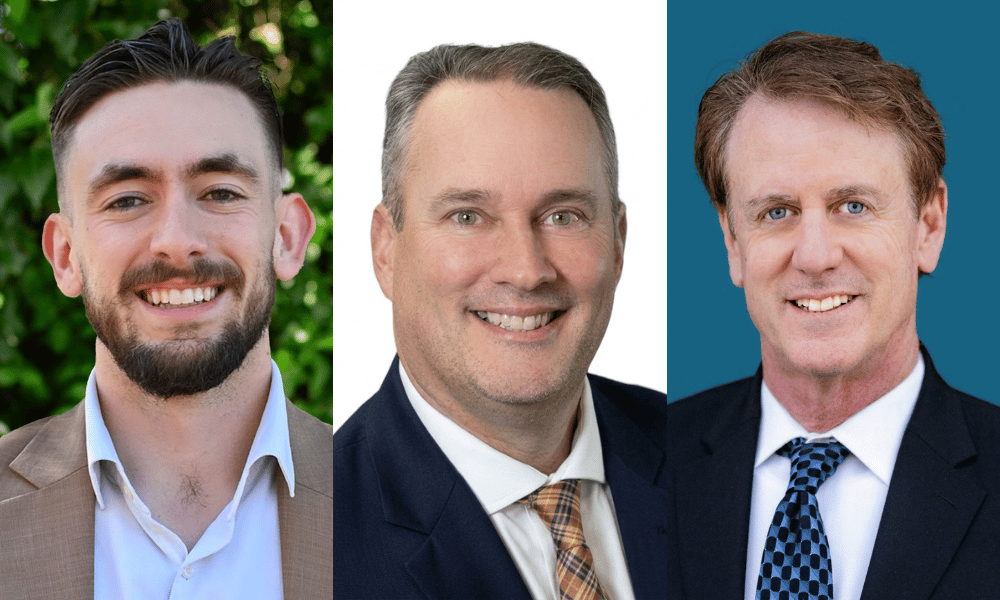
Ryan Botzong, vice president and financial advisor at Austin, Texas-based 49 Financial, said that for clients whose residence accounts for 60% to 70% of their net worth, he now plans on the assumption that the equity is considerably less liquid than it has been historically. His answer is a short-term reserve in cash or bonds, giving those clients room to maneuver if they are forced to sell into a slower market.
"With Treasury yields where they are, we're seeing the value of a home as being a lot more about utility - peace of mind and emotional stability - than about investment growth. I can say that personally, too. Looking at a home, it's a lot more important to think of it as an emotional utility, for kids, for gatherings, for family, than as a return on investment. That said, a home can still be a good inflation hedge, even with Treasuries rising. What's crucial, if you're thinking about buying a house, is making sure you plan to stay in it for the long term, not moving from job to job and house to house," Botzong said.
Jim Worden, chief investment officer at The Wealth Consulting Group in Las Vegas, draws a firmer line. In his view, clients generally should not treat their home as an investable asset in a portfolio or financial plan unless they have borrowed against it and invested the proceeds.
He said advisors should explain the risks of borrowing against any illiquid asset, and build plans with enough flexibility to absorb a common reality: homes often take longer to sell than owners hope, and fetch less than they expect.
"Investing in a home can still make a lot of sense, based on how much money is put down, the location of the home, the growth of the local market, and housing generally appreciates over time, which can be a good hedge against inflation. As always, investors should do due diligence not only on the property, but on the lender, examining the rate and structure of the mortgage. For those not making sufficient income, investors should avoid interest only or negative amortizing loans and buy a home that is well within their income," Worden said.
Vance Litchfield, director of wealth management and financial planning at Sagient, a wealth manager based in El Segundo, California, treats the home as a core part of a client's balance sheet but not as a liquid investment. Because higher rates can limit a household's mobility, he folds the property into the full plan – retirement income, cash flow, debt management and estate planning – rather than judging the investment portfolio in isolation.
He also sees the bond market offering clients a credible alternative to leaning on real estate for growth.
"Higher Treasury yields make fixed income more attractive from both an income and risk-management perspective. That reinforces the importance of diversification rather than assuming real estate should continue to be the dominant investment simply because it has historically appreciated. Housing can provide long-term appreciation and utility, but it also carries concentration and liquidity risks. The right question is how the home fits with the client's overall goals, cash flow, and risk tolerance," Litchfield said.
The pressure is sharpest for clients nearing retirement whose wealth is concentrated in a single property. Planners have long argued for folding home equity into a retirement income plan, and 7% mortgages make the exercise more urgent.
Botzong said downsizing can make sense for some of those clients, though not all, particularly one- or two-person households that no longer need the space.
"Ultimately, retirement is about having optionality. You may have a high net worth on paper because your house elevates it, but if you don't have liquidity, you don't have optionality. You have constraints. We don't call that retirement. Liquidity is what can give you the freedom to be with the people you care about and do the things you're passionate about in that time of life," Botzong said.
Worden said house-rich, cash-poor clients may want to explore ways to extract some equity by borrowing against the property, an approach that, handled prudently, can meet cash flow needs without leaving them overextended.
Litchfield frames the goal as converting balance-sheet wealth into lasting flexibility. Depending on the client, that could mean downsizing, a home equity strategy, refinancing when conditions allow, or simply building enough liquid investments outside the house.
"The key is to avoid having a large percentage of retirement wealth tied up in an asset that may be difficult or costly to access when income is needed," Litchfield said.

The quality of AI ROI measurement depends on pre-deployment decisions around business outcomes, leadership alignment, and establishing trusted information, among other factors.

A state-by-state analysis of retail investor behavior reveals AI-powered research tools are reshaping how clients approach investment decisions.

LPL picks up $1.1B from Wells Fargo's independent channel as the wirehouse gains a $410M family team from UBS.

Most Americans want to age at home but few have a financial plan to pay for it, according to new research.
Halbert Hargrove senior wealth advisor weighs in on the products' guaranteed income upside, the operational drag and his wish list for carriers.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

