
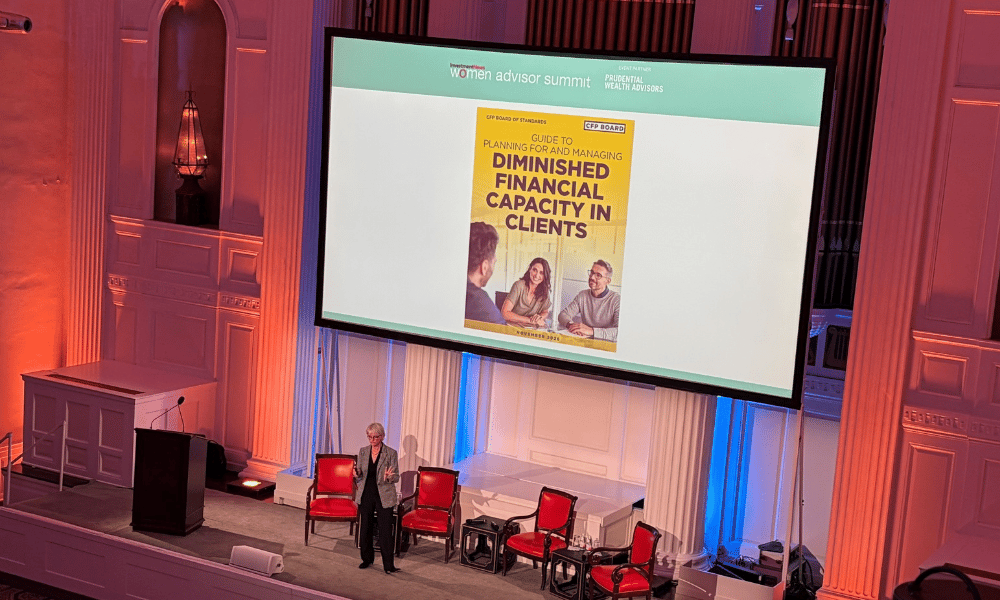
Advisors should be fully prepared to spot the first signs of clients’ cognitive decline, according to Carolyn McLanahan, founder of Jacksonville, Fla.-based Life Planning Partners.
Speaking during InvestmentNews’ recent Women Advisor Summit McLanahan, who is also an M.D., urged advisors to be on the lookout for signs of decline. “What we do know is that financial management skills are the first to go,” she said. “So it is important that in your office, everybody be trained on how to recognize an issue.”
“We have to identify it early – once you identify it, you can’t sit on it,” she added, noting that there are steps that advisors can take to protect themselves and their clients.
“You have to have a trusted contact form for every client,” McLanahan said. “You do it during the estate planning review … once serious cognitive decline steps in, good luck if you haven’t prepared.”
McLanahan, who serves on the CFP Board Resource Commission, explained that the organization has been working on a guide to help advisors deal with this situation. The Guide to Planning For and Managing Diminished Financial Capacity in Clients identifies red flags for diminished financial capacity, warning signs for financial exploitation as well as best practices for managing the engagement once the client shows signs of diminished capacity.
McLanahan, who was awarded the Alexandra Armstrong Lifetime Achievement Award by Investment News in 2024, also discussed the broader aging-related questions that advisors should be asking their clients.
Key questions include “where are you going to age?” with McLanahan explaining that her firm arranges a visit to a nursing home. “The nursing home is actually very excited that people are coming to visit - they actually provide lunch and we get a tour,” she added.
Other important questions are “who's going to help them with financial decisions?” and “who's going to help them with healthcare decisions?” she said. Transportation planning is also important, according to McLanahan. “Where I live in Jacksonville, Florida, you can't get around without a car - and so having a conversation about ‘what are you going to do if you can't drive’?”
Armed with this information, advisors can plan for long-term care costs, according to McLanahan.
Certainly, there is a growing need for financial advice as Americans live longer. According to the 2020 U.S. Census, one in six people in the U.S. were 65 and over. Census data also show that the U.S. population aged 65 and over grew between 2010 and 2020 at the fastest rate since 1880 to 1890, reaching 55.8 million, a 38.6% increase in just 10 years.

The best tax plan asks not only how much a client could save, but what they would have to give up to save it.

A 20-year financial services veteran brings values-driven planning expertise to the St. Louis-based RIA.

New research shows a 71% plunge in actions in fiscal year 2026, with total settlements the lowest since the database began.

An Ohio-based advisor departs Edward Jones to build an independent firm focused on retirees and business owners.

Broker-dealer enforcement actions surged 66% as the SEC and state regulators cracked down on Ponzi schemes and digital asset fraud.
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.

