
The great wealth transfer is no longer a projection on an advisor’s whiteboard. It is closing on houses. The question clients are bringing to advisors has shifted from whether to help their children buy a home to when, and how.
The National Association of Realtors’ 2026 Profile of Home Buyers and Sellers, released Nov. 5, 2026, found that a record 10% of first-time buyers offered all cash for homes between July 2025 and June 2026, the highest share since NAR began tracking the statistic in 2003. Family money is driving much of that. Among first-time all-cash buyers, 28% used an inheritance to fund the purchase, compared with just 9% of financed buyers. Across all first-time buyers, 10% used an inheritance, also a record and the fourth straight annual increase. One in four drew on a gift or loan from family and friends.
The heirs, however, are not young. The share of first-time home buyers rose slightly to 22% from last year’s record low of 21%, while the typical age of first-time buyers remained at an all-time high of 40. For first-time buyers who financed a purchase it was 38, while for those who paid all-cash it was 54.
For financial advisors, that age gap is the planning problem. It echoes earlier InvestmentNews reporting that trillions in home-based wealth are on the move while families avoid talking about it.
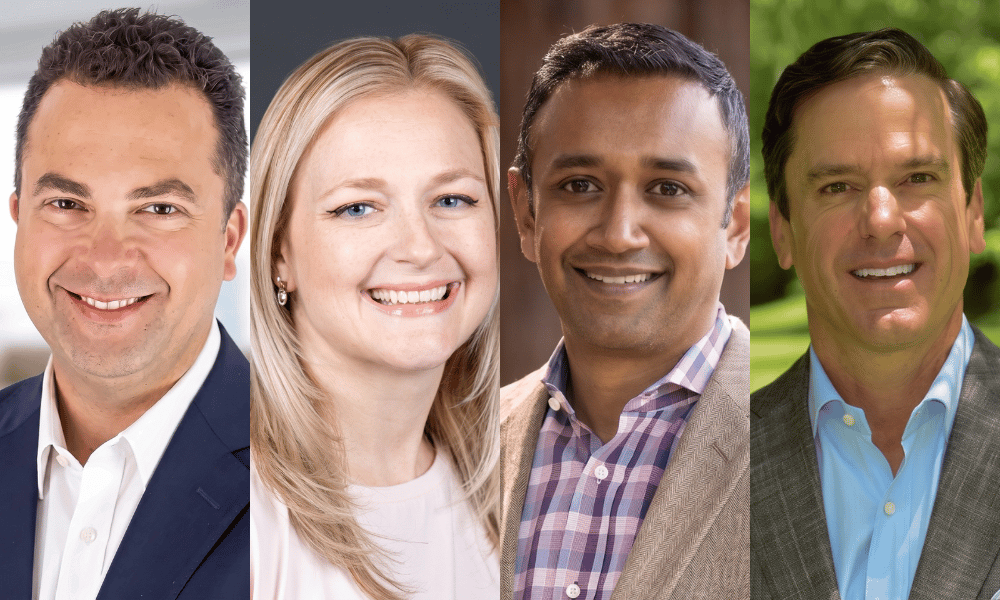
Peggy Sizow, chief fiduciary officer at National Advisors Trust, said the right structure depends mostly on the child: their age, when they plan to buy and their overall financial position.
A gift made now gives the child immediate control of the money. The parent gives up the assets right away and must file a gift tax return. Under current rules, a gift above the annual gift tax exclusion ($19,000 in 2026 or $38,000 if the gift is split with a spouse) uses a portion of the individual’s lifetime exemption ($15 million in 2026). Both thresholds rise next year. The annual exclusion increases to $20,000 per recipient, and the lifetime exemption to $15.48 million per individual.
A family loan, Sizow said, limits the child’s control and turns the gift into something incremental. Parents also have to decide in advance how they would handle a default or whether they might forgive the debt. Leaving the money in the estate gives the parent the most control, since the plan can change until death. The cost is that the help arrives later, as an inheritance rather than a gift.
Matt Cavanaugh, managing partner and director of investments at XXI Wealth, starts with two filters. “We start with two questions: what is the client trying to accomplish, and what can they give without putting their own plan at risk? If the money really is surplus, a gift now is often the cleanest choice, and clients enjoy seeing it at work. An inheritance is a check you will never see cashed. A gift can be a front door you get to walk through,” he said.
On lending, Cavanaugh insisted on formality. “A family loan can make sense when parents need the money back or want to treat siblings evenly. It should be a real loan, with a written note and at least the IRS applicable federal rate. Handshake deals are how families end up in uncomfortable situations,” he said. The applicable federal rate (AFR) is the minimum interest rate the IRS publishes each month for loans between related parties.
Cavanaugh noted that waiting still suits some families. “Leaving it in the estate is still right for some families, especially with appreciated assets that may get a step-up in basis. The tradeoff is that the help often arrives after the kids need it most,” he said.
Cavanaugh said many clients picture their children inheriting while still starting out. With longer lifespans, the money is more likely to land when those children are in their 50s or 60s and planning their own retirement.
“Most people picture their kids at 25 when they inherit. More and more, they’ll be closer to 60. So we tend to ask clients a simple question: when will this money matter most to your kids? Often the answer is sooner, for a home, a business, or the grandkids’ education. Money that shows up at 30 can change a life. At 60, it often just changes a balance sheet,” he said.
Sizow made a similar point. “The age of the heir changes the plan, as the timeline is different. An older child likely needs the home sooner, is more responsible, and has less years to reap the benefit of a gift,” she said.
Roshan Weeramantry, founding partner at Hyphen Wealth Management, serves clients mostly in the San Francisco Bay Area, where entering the housing market is especially hard. He said many clients in their 60s and 70s want to help their adult children now rather than later. His firm tests that impulse against the numbers.
“When a client tells us they want to help their kids, we immediately go to their EMoney plan and we build out ‘what if?’ scenarios to model out what they are thinking. We beat up the numbers to make sure that giving away funds does not threaten their own retirement plan. Depending on the size of the gift, we may suggest a family loan to avoid taking a sizable capital gains hit,” Weeramantry said.
All four advisors agreed that the conversation matters as much as the structure. That view is backed by recent research showing inheritance conflict is the rule, not the exception among affluent families.
“The worst time for your kids to learn about your money is at the reading of the will,” Cavanaugh said of his approach to clients. He recommends that families begin with values before dollar amounts and that the advisor host the family meeting. “Helping a child buy a home is often the best opening. A down payment is the easiest wealth-transfer conversation a family will ever have, because everyone can see what the money is for,” he said.
Sizow encourages clients to share their finances and estate plans with their children once they are comfortable doing so. “Ideally, their trustee or executor will be in the room when the drafting discussions are happening,” she said.
Weeramantry brings clients’ children into planning meetings as the parents age. “The more knowledge they have, the more prepared they will be to help steward the family wealth appropriately,” he said. That approach mirrors what the best wealth managers and advisors under 40 are prioritizing ahead of the handoff.
Brian Gately, managing partner at Anchyra Partners, argued that a parent is the best judge of whether a child can handle money. If the child is a productive adult who is already named in the estate plan, he said, there is little reason to wait.
“A sad, unspoken, and unintended consequence of waiting until your death to pass assets is having children looking forward to that outcome in order to unlock wealth,” Gately said. “If you’ve taken the time to build an estate plan, take the time to explain it to your children. Their input may surprise you and an honest conversation may lead you to make changes you hadn’t considered.”
Valerie Bevan joins LPL Financial after more than 30 years in financial services, citing platform flexibility and advisor independence.
A new independent benchmark finds a widening gap between AI leaders and laggards across 30 of the world's largest investment firms.

Jamie Price says LPL shifted its Commonwealth target from advisors to assets, letting 16 months of growth mask departures

80% of Baby Boomers prefer guaranteed income over growth investments, yet only 17% hold an annuity, leaving protection gaps for financial advisors to close

“Even with all the work done before hand, this is still a bit stressful,” one advisor said.
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

