
Deferring money management responsibilities to a spouse during marriage may seem at first convenient, but it can expose women to several severe financial risks if the marriage ends in divorce, a new study said.
A BMO survey released last week showed only 36% of respondents who deferred money management responsibilities to their spouse felt confident managing their finances during and after the divorce, compared to nearly 64% who of those who helped manage household finances during their marriage. On the flip side, those women who split money management duties equally during the marriage were more likely (68%) to report that their financial confidence remained the same after the divorce, versus during the marriage.
The findings for the study were based on the views of 362 women, all of whom had investible assets of more than $1 million and divorced their spouse within the last five years.
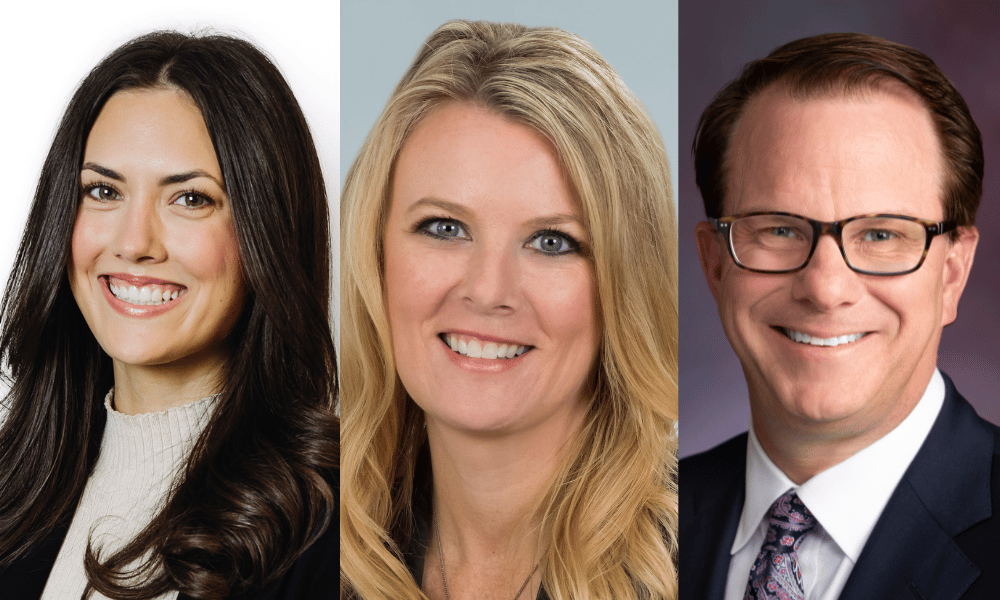
“Financial confidence doesn’t happen by accident; it’s built through active participation. Women who take a hands-on role in managing their household finances are far better positioned to navigate life’s transitions,” said Amy Hale, executive sponsor of women & wealth at BMO Wealth Management.
Among the key dangers faced by women who substantially defer financial responsibility to their spouse during their marriage are a lack of financial literacy and confidence, limited visibility into financial health, vulnerability in navigating a divorce settlement, and inheritance and estate planning issues.
Retirement and tax liabilities could also cause problems, according to Hale.
“Women may not know if enough is being saved for retirement or if they’re named on all accounts, leading to financial insecurity later in life, especially given women’s longer lifespan. And if the spouse makes poor financial decisions, both partners may be held liable, and women could face unanticipated legal consequences or tax burdens,” Hale said.
Madison Evans, financial advisor at Blanke Schein Wealth Management, says one major risk for women who neglect to learn their family’s true financial state is being unprepared for life-altering events like divorce or the spouse's death. This lack of preparedness can often lead to feelings of being "blindsided" by sudden financial stressors and scrambling to rebuild from a false sense of security.
“This dependence puts future financial security at risk, as women who defer long-term decisions such as investments or retirement planning may face setbacks in wealth accumulation and independence. In divorce, this can translate to a more difficult post-marital financial navigation, including unequal asset division or delayed recovery,” Evans said.
Michael Landsberg, partner and chief investment officer at Landsberg Bennett Private Wealth Management, points out that women often live longer than men, so they need to consider their lives without their husband, either by death or divorce. As a result, women should not wait to accumulate the necessary financial knowledge for that probability.
Secondly, Landsberg notes if a woman has delegated the money management to the husband, the advisor will typically stay with the one he has the better relationship with – and that will likely be the husband.
“If she hasn’t been involved or regularly attended meetings, she will be in a situation where she now has to make important money decisions by herself and will not have a trusted advisor to help guide her through it,” Landsberg said.
Becoming more active in household finances doesn’t require taking over everything, according to BMO’s Hale. First and foremost, she advises clients be at the "financial table" so they understand their full financial picture - budgeting, saving, investing, insurance, and retirement.
She also recommends they be present in meetings with financial advisors, tax professionals, or estate planners to ensure their voice is heard and interests are represented.
“Keep a secure digital log or a binder with account info, passwords, insurance policies, and estate plans. And educate yourself by reading personal finance books, listening to podcasts, and attending events,” Hale said.
Along similar lines, Evans suggests women educate themselves on basics such as credit building, investing, and debt management utilizing resources like free online courses, books, and podcasts.
“We always encourage couples to attend all financial meetings together whether that is meetings with financial advisors, tax professionals, or attorneys. Regularly revisit your strategy, and advocate for equitable involvement by volunteering for specific tasks, such as bill payments or tax prep. These steps not only empower you but also strengthen the household's overall financial health,” Evans said.
Divorce can be both emotionally and financially destabilizing, which is why one needs a trusted team of professionals at their side. Hale stresses assembling a team of advisors early as a crucial first step.
“Connect with a family law attorney, a financial advisor, and an accountant, all of whom can work together alongside you to ensure that your best interests are looked after in the divorce process and your settlement achieves your financial goals and protects your future,” Hale said.
Landsberg, meanwhile, notes that “emotions run high in divorces” so it is critical to have a deliberate process to walk through every account or position. Taking one account over another because of attachment or sense of ownership is a common mistake emotional people make.
“Take a step back and evaluate each account dispassionately and see what the net benefit to you is. If you aren’t able to do that on your own, employ a fiduciary advisor to help you through the process,” Landsberg said.

Thrivent Investment Management Inc. in May fired Nicholas Hale, according to his BrokerCheck profile.

About 70 bank and credit union advisors move to the Raymond James platform, while a $480M New Jersey team goes independent with LPL

The best tax plan asks not only how much a client could save, but what they would have to give up to save it.

A 20-year financial services veteran brings values-driven planning expertise to the St. Louis-based RIA.

New research shows a 71% plunge in actions in fiscal year 2026, with total settlements the lowest since the database began.
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.

