
Let’s flip the script, shall we?
How about we hear what the next generation generation of financial advisors has to say about the coming talent shortage for once, instead of focusing on the retiring ones?
To quickly review, over one-third of advisors, representing 41% of industry assets, are expected to retire within the next decade, according to a recent Cerulli study. Among them, 15% plan to sell their practices externally, a figure that rises to 33% for independent RIAs, according to the research.
To make up for all the wealth management talent headed for the beach or the mountains (or wherever RIAs spend their golden years these days), the RIA industry will need to add over 70,000 new staff over the next five years based on current growth rates, according to the latest Schwab study.
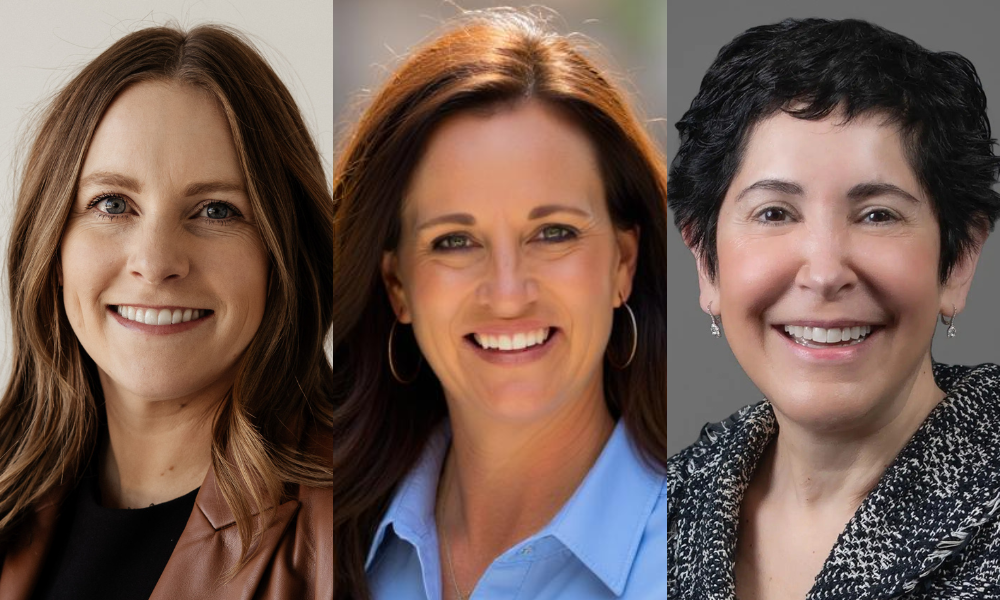
As to what the younger generation is thinking about when it comes to ownership and the transfer of business, Alana Macy, partner and wealth advisor at Bloom Wealth Advisors, believes the challenge lies in affording these businesses, especially with their current “sky-high valuations.”
“While some advisors may attempt to build firms from the ground up, the growing dominance of larger firms and the increasing demand for bigger teams makes this path more challenging than it was for G1 advisors in the 80s and 90s. G2 advisors are eager to own businesses, but they may need to get creative in finding ways to make this happen,” Macy said.
Elsewhere, Shanna Kehoe, partner and wealth advisor at Carson, believes aligning with the right firm and culture is critical for the up-and-coming generation of advisors.
“It can significantly shape the path toward ownership and leadership. While not everyone may be thinking about succession right away, the desire for ownership is there — especially when they see a clear, supportive path forward,” Kehoe said.
That said, Debbie Taylor, Carson Wealth’s chief tax strategist and managing partner, notes that a substantial contingent of the younger generation values “quality of life” and may not view the entrepreneurial dream of owning a business in the same way as the baby boomers did. In many instances, she believes the coming generation of wealth managers would prefer job security and a less stressful lifestyle overall.
In addition, she points out that working in a corporate environment has become a lot more welcoming to younger professionals than 25 years ago. Advisors can work from home or have hybrid arrangements, for example. They also have generous PTO and even sabbaticals.
“These benefits, coupled with the opportunity to grow professionally, create an attractive situation that takes the luster away from running a business and being self-employed,” Taylor said.
With so many advisors exiting the industry in the next few years, Macy expects it will face a significant talent shortage, similar to the one currently being experienced by CPAs. That void offers new entrants incredible opportunities in her view and more of the younger generation should be looking at advising as a promising career.
“To attract this talent, we need to mentor aspiring advisors, showcasing the career’s flexibility, independence, creativity and the fulfillment of helping people. We should also tap into career transitioners and those without traditional financial backgrounds, as they often bring fresh perspectives and invaluable skills,” Macy said.
Macy adds that she is particularly passionate about encouraging more women to join the industry and “showing them how wealth management can be a rewarding career alongside motherhood.”
One of the biggest roadblocks for young advisors, especially female ones, is attracting new business. In order to overcome this barrier to entry, Taylor suggests the industry should create a professional environment that de-emphasizes sales similar to other professions that have higher representation of women such as medicine or law.
“The industry would also become more attractive to the younger generation if there was a wider diversity of leaders, which again could happen if the path to the top was not so narrowly defined,” Taylor said.
To attract younger talent, Kehoe believes the wealth management industry must prioritize work-life balance and flexible work arrangements. Millennials and Gen Z value autonomy, mental health, and purposeful work environments. Firms can appeal to these preferences by offering remote or hybrid work, flexible schedules, and reducing early-career pressure around sales targets, according to Kehoe.
“Leveraging technology to streamline tasks and providing mental health resources further support sustainability in the advisor role. By fostering a culture that respects personal time and well-being, the industry can promote long-term career satisfaction and increase retention among the next generation of advisors,” Kehoe said.

The financial advice industry has been facing inquiries into its cash sweep programs for years now.

Procyon adds $415 million in assets under management in New Jersey while Savant picks up a $213 million Southern California planning firm

With a growing number of real estate-rich Baby Boomers aging into retirement, some advisors may be failing to consider all the options available for those clients' assets.

Cornerstone Advisors study reveals compliance bottlenecks stall campaigns weeks after customer opportunities close.
A father-daughter trio managing approximately $700 million joins the Atlanta-based fee-only RIA, establishing its Austin foothold.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

