
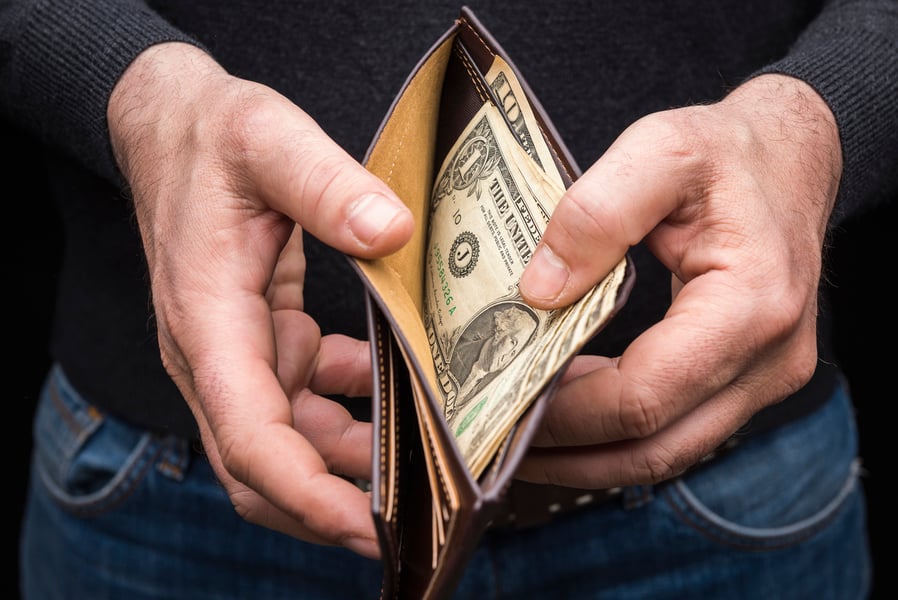
Despite a rallying stock market and signs that inflation is easing, most Americans remain pessimistic about the economy as affordability concerns continue to dominate household finances ahead of the 2026 midterm elections.
According to CNBC’s latest All-America Economic CNBC’s latest All-America Economic Survey, 61% of Americans say they are pessimistic about the current economy and its future, the highest share recorded since December 2023. Just 25% say they are optimistic, reflecting continued concern over the cost of everyday necessities despite recent improvements in broader economic indicators.
Those concerns are translating into changes in consumer behavior. Nearly half of respondents said they have to cut back on essential purchases such as food and medical care, up six percentage points from CNBC’s April survey. Two-thirds said they are spending less on discretionary purchases like dining out and entertainment, while more Americans also reported reducing travel and relying more heavily on credit cards.
The survey suggests those financial pressures are weighing on voters’ views of the economy heading into the midterm election cycle. President Donald Trump’s approval rating stood at 40%, while 60% of respondents disapproved of his handling of the economy. His approval on inflation and the cost of living was even lower, with 68% disapproving.
Although dissatisfaction with the economy remains widespread, the poll found Democrats hold only a narrow four-point advantage over Republicans when respondents were asked which party should control Congress. Both Democratic and Republican pollsters who conducted the survey noted that voters remain highly polarized, limiting large shifts in party preference despite concerns about economic conditions.
Affordability also ranked as voters’ top issue. Democrats held a modest advantage on addressing the cost of food and groceries, while Republicans maintained a sizable lead on immigration and border security, highlighting the different issues driving each party’s supporters.
Separate research from CapWealth suggests affordability pressures are spreading across income levels. The firm's new white paper, which incorporates federal data, consumer surveys and its own analysis, found that rising housing costs, debt burdens and persistent inflation are increasingly squeezing households earning $100,000 or more annually.
Among the data cited in the report, U.S. household debt has climbed to a record $18.8 trillion, according to the Federal Reserve Bank of New York, while credit card delinquencies have reached a 16-year high. The report also points to housing affordability as a growing challenge, noting that median home prices have exceeded $400,000 and that the medan-income family now spends roughly one-third of its earnings on housing.
While headline economic indicators have improved, many Americans continue to feel financial strain in their daily lives. With affordability remaining a central concern across income groups, economic conditions are likely to remain a key issue for voters as the midterm elections approach.

Trevor Uhls pleaded guilty to one count of wire fraud and one count of money laundering.

Osaic and LPL Financial routinely square off in recruiting advisors from other firms as well as from each other.

Meanwhile, Wealthspire's Ground Control business picks up a $1B private wealth firm in London, and Modern Wealth deepens its presence in California.
The $100B-plus mega-RIA is folding custom portfolios, daily tax-loss harvesting and unified managed accounts into its Aspen advisor tech platform
From using projects as strategic thinking exercises to real-world challenges as problem-solving exercises, indie firms can make for more powerful talent incubators.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

