
Financial advisors are on pace to add roughly $2 trillion to alternative-investment holdings by the early 2030s, according to Cerulli Associates research, and a growing share of that capital is expected to flow into private infrastructure — power, digital infrastructure and other essential assets — as the strategy increasingly competes with private credit for a bigger slice of client portfolios.
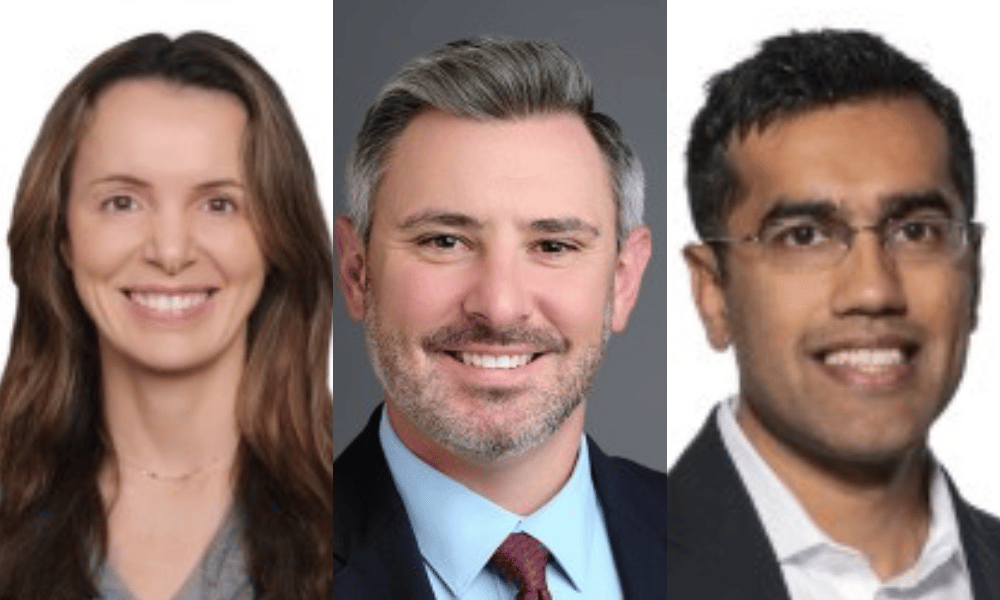
Doug Huber, deputy chief investment officer at Wealth Enhancement, said the right allocation to private infrastructure depends less on a target number than on what the client is trying to accomplish. Before discussing percentages, he starts by determining whether the added complexity and illiquidity fit the client's liquidity needs, risk tolerance and existing private-market exposure.
Huber frames the conversation around five objectives: return enhancement, income generation, diversification, inflation protection and a total portfolio solution. Depending on which applies, infrastructure might make up 10% to 50% of a private-markets program, while the overall private-markets allocation typically represents 5% to 15% of a client's total assets.
"We would typically start near the lower end and build the allocation over time and across multiple vintage years," Huber said. "The funding source should reflect the risk being taken: core infrastructure may replace some fixed income or public real assets, while value-add infrastructure should generally be treated more like an equity or private-equity allocation."
Dinesh Ramasamy, a partner at Pantheon, said allocation size should ultimately track a client's own risk and return appetite, though he noted private infrastructure has historically shown low correlation to equities and fixed income and lower volatility than other private-market strategies. Ramasamy pointed to infrastructure secondaries as a way for advisors to gain a differentiated entry point, offering exposure to established, operating assets with contracted cash flows and visible performance histories.
Huber said private infrastructure was historically an institutional, income-generating allocation built around mature assets such as toll roads, airports and regulated utilities. The opportunity set has since broadened to include data centers, distributed energy and grid modernization, some of which require active development rather than passive ownership.
"The first question advisors should ask is what the fund actually owns, because the infrastructure label can describe anything from a stable, contracted asset to a speculative development project," Huber said. He cited overpaying for popular assets, excessive leverage and underestimated construction timelines as key risks, adding that fees, valuation practices and liquidity terms deserve close scrutiny as semi-liquid vehicles expand retail access to illiquid assets.
Demand tied to artificial intelligence has become a central storyline in infrastructure investing, but sources cautioned advisors against treating every AI-linked deal as automatically attractive. Huber said the better test is whether a project has secured power, grid access, permits and contractual revenues that compensate investors for construction and operating risk — and the more attractive opportunities may sit in supporting assets such as power generation, transmission and cooling rather than the priciest data-center projects themselves.
Ramasamy drew a similar distinction. "Power, utilities, renewables, transmission, and data centers are the most straightforward way to play the AI theme," he said. "Assets like chips, models, and applications carry a different risk profile entirely and shouldn't be evaluated through an infrastructure lens simply because AI is the tailwind."
Irina Zilbergleyt, managing director and global head of distribution and product strategy for ISQ OpenInfra at I Squared Capital, said the firm uses a simple test for what counts as true infrastructure: essential demand plus a durable moat, whether physical or contractual. She cited findings from the firm's ISQ OpenInfra Index — a survey the company says drew responses from 250 advisors — in which roughly half cited digital infrastructure and AI-linked demand as a driver of client interest.
Zilbergleyt noted that institutional investors have typically funded infrastructure allocations from fixed income and credit sleeves, reflecting the asset class's traditional role as a source of income and stability. But she said survey respondents increasingly cite capital appreciation, rather than income alone, as infrastructure's primary role — suggesting the funding source for many retail portfolios may reasonably blend both fixed income and equity.
Donated SpaceX stock generally can’t be refused or sold for years, leaving advisors to explain concentration risk to families
Aging populations and underfunded systems are forcing wealth managers to rethink how they prepare clients for retirement.
A new Morgan Stanley survey signals a fundamental shift in how employees view retirement benefits - and raises the stakes for plan advisors.

Proposition 40 wealth tax could raise $30 billion, not $100 billion, as departures erode the base and voters remain split.

Jump is piping FMG marketing content into post-meeting workflows as Zocks opens its platform to more than 32,000 LPL financial advisors.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

